Thinking About Waiting for Lower Mortgage Rates? Read This First.
Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating. But it's a real possibility.
A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today's forecasts, that may not happen. And you should know that before you decide what to do.
Let's look at why experts don't expect a dramatic drop in rates, and the options that could help you buy anyway. Because even if rates don't fall, you can still move. Here's how.
1. Mortgage Rates Aren't Expected To Fall in a Meaningful Way
If you're waiting for rates to fall, you're not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.
The challenge is, that's not what the experts who study mortgage rates every day are expecting.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):
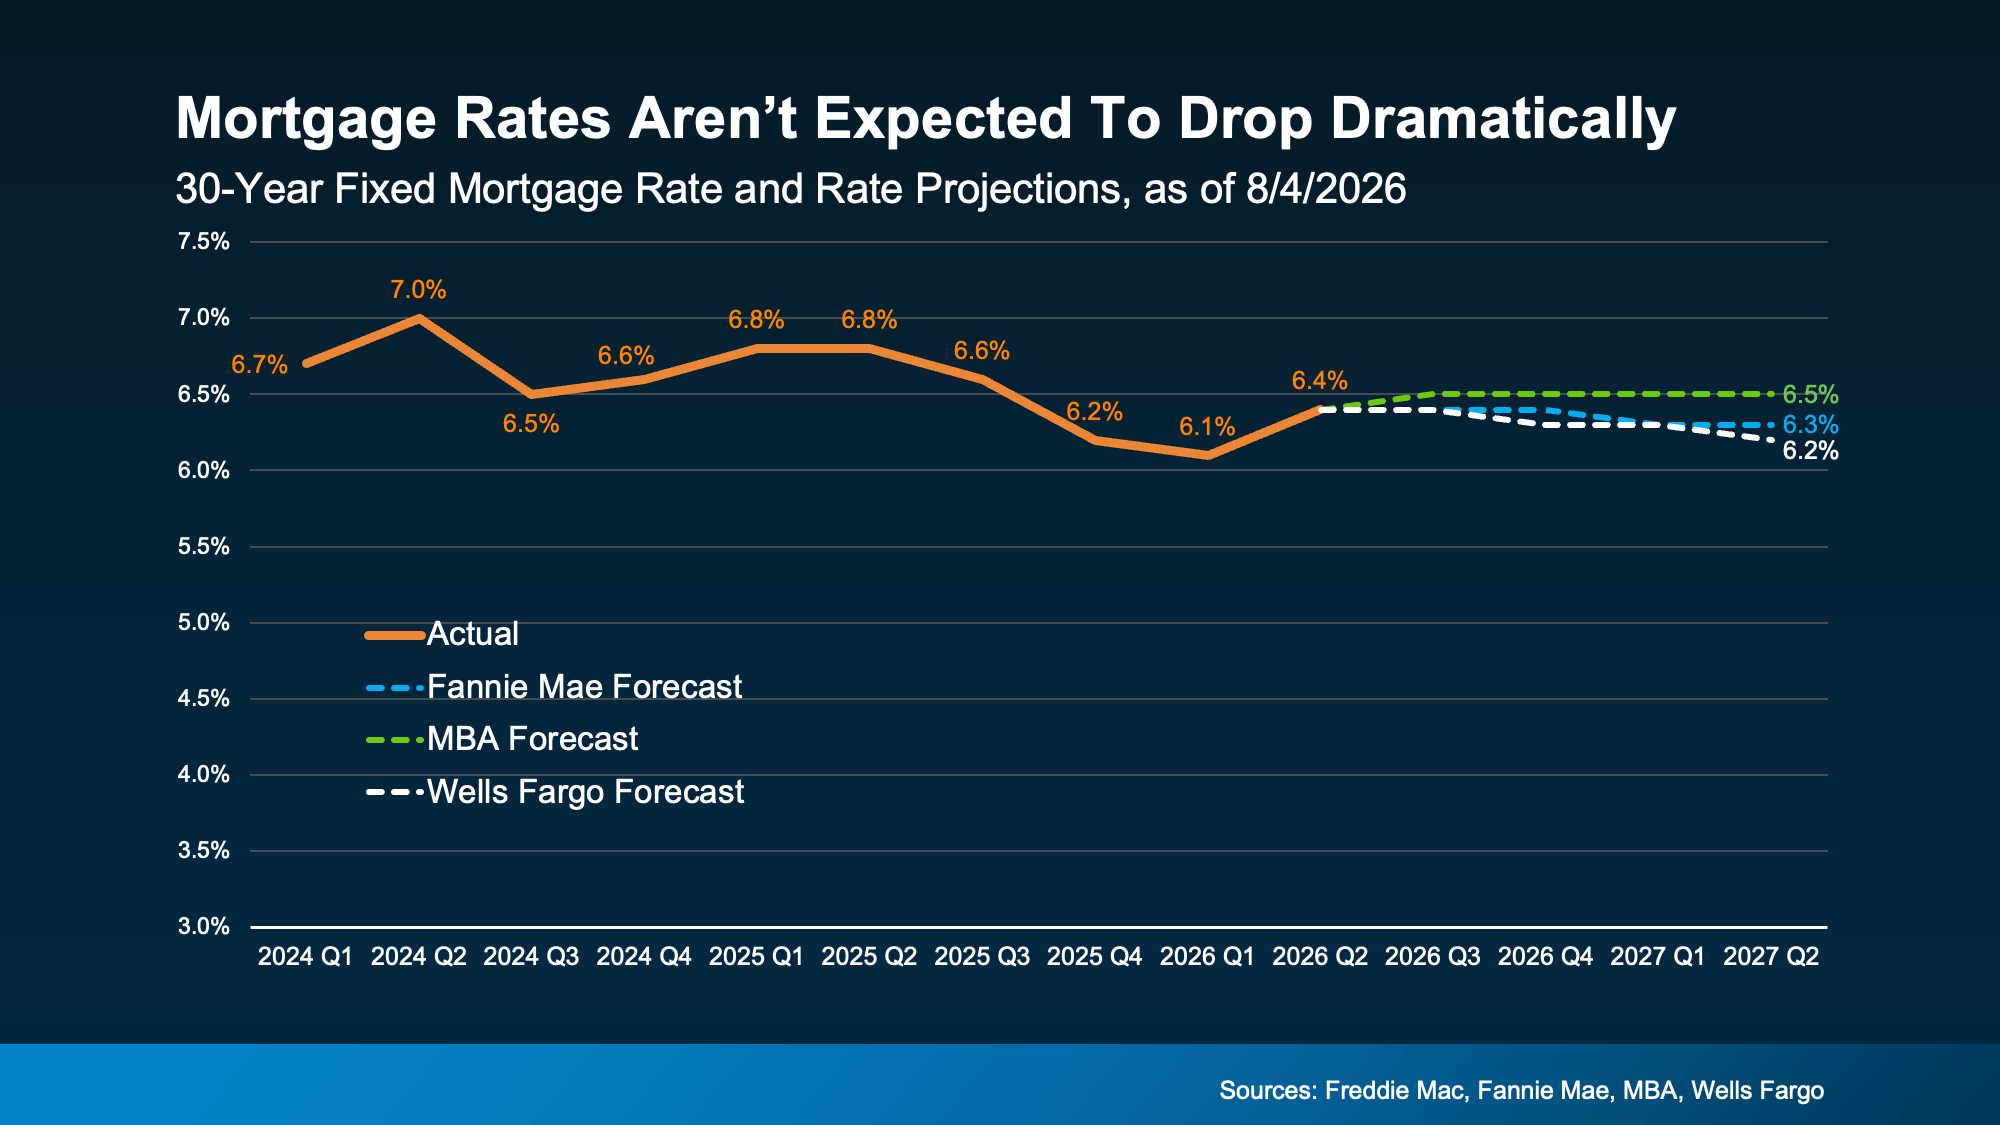
Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren't pointing toward the kind of dramatic rate drop many buyers are waiting for.
Could rates move a little? Of course. But if you're holding out for a bigger drop, today's forecasts suggest you may be waiting a lot longer than you expect.
2. Inflation Is Still Elevated, and That's Working Against Lower Rates
One reason experts aren't expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):
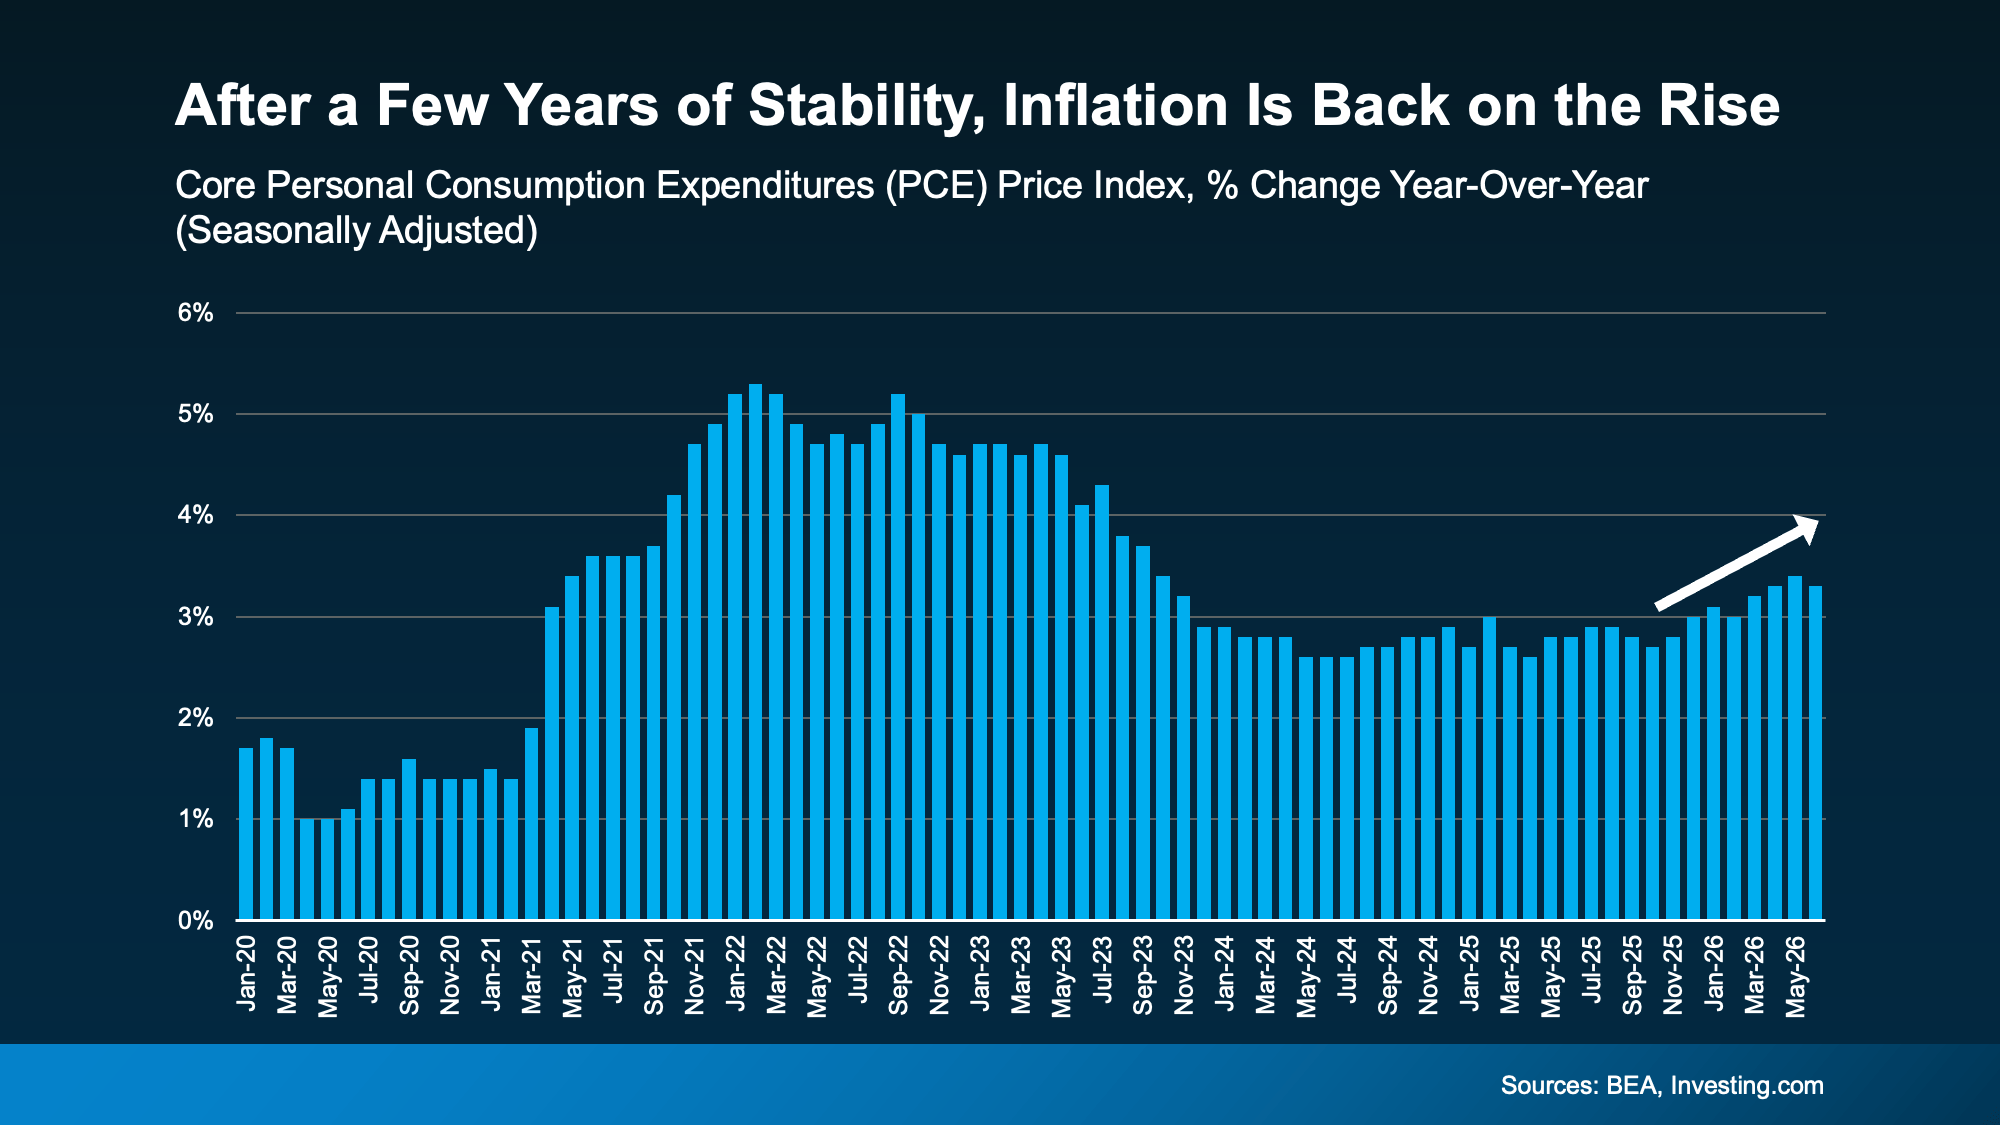
In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn't in place today. That helps explain why experts aren't forecasting the kind of meaningful decline so many buyers are hoping for.
3. Today's Rates Aren't High, They're "Normal"
And this may be the biggest mindset shift of all. The reality is, while today's rates may feel high compared to a few years ago, they're not high. They're normal.
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we're actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):
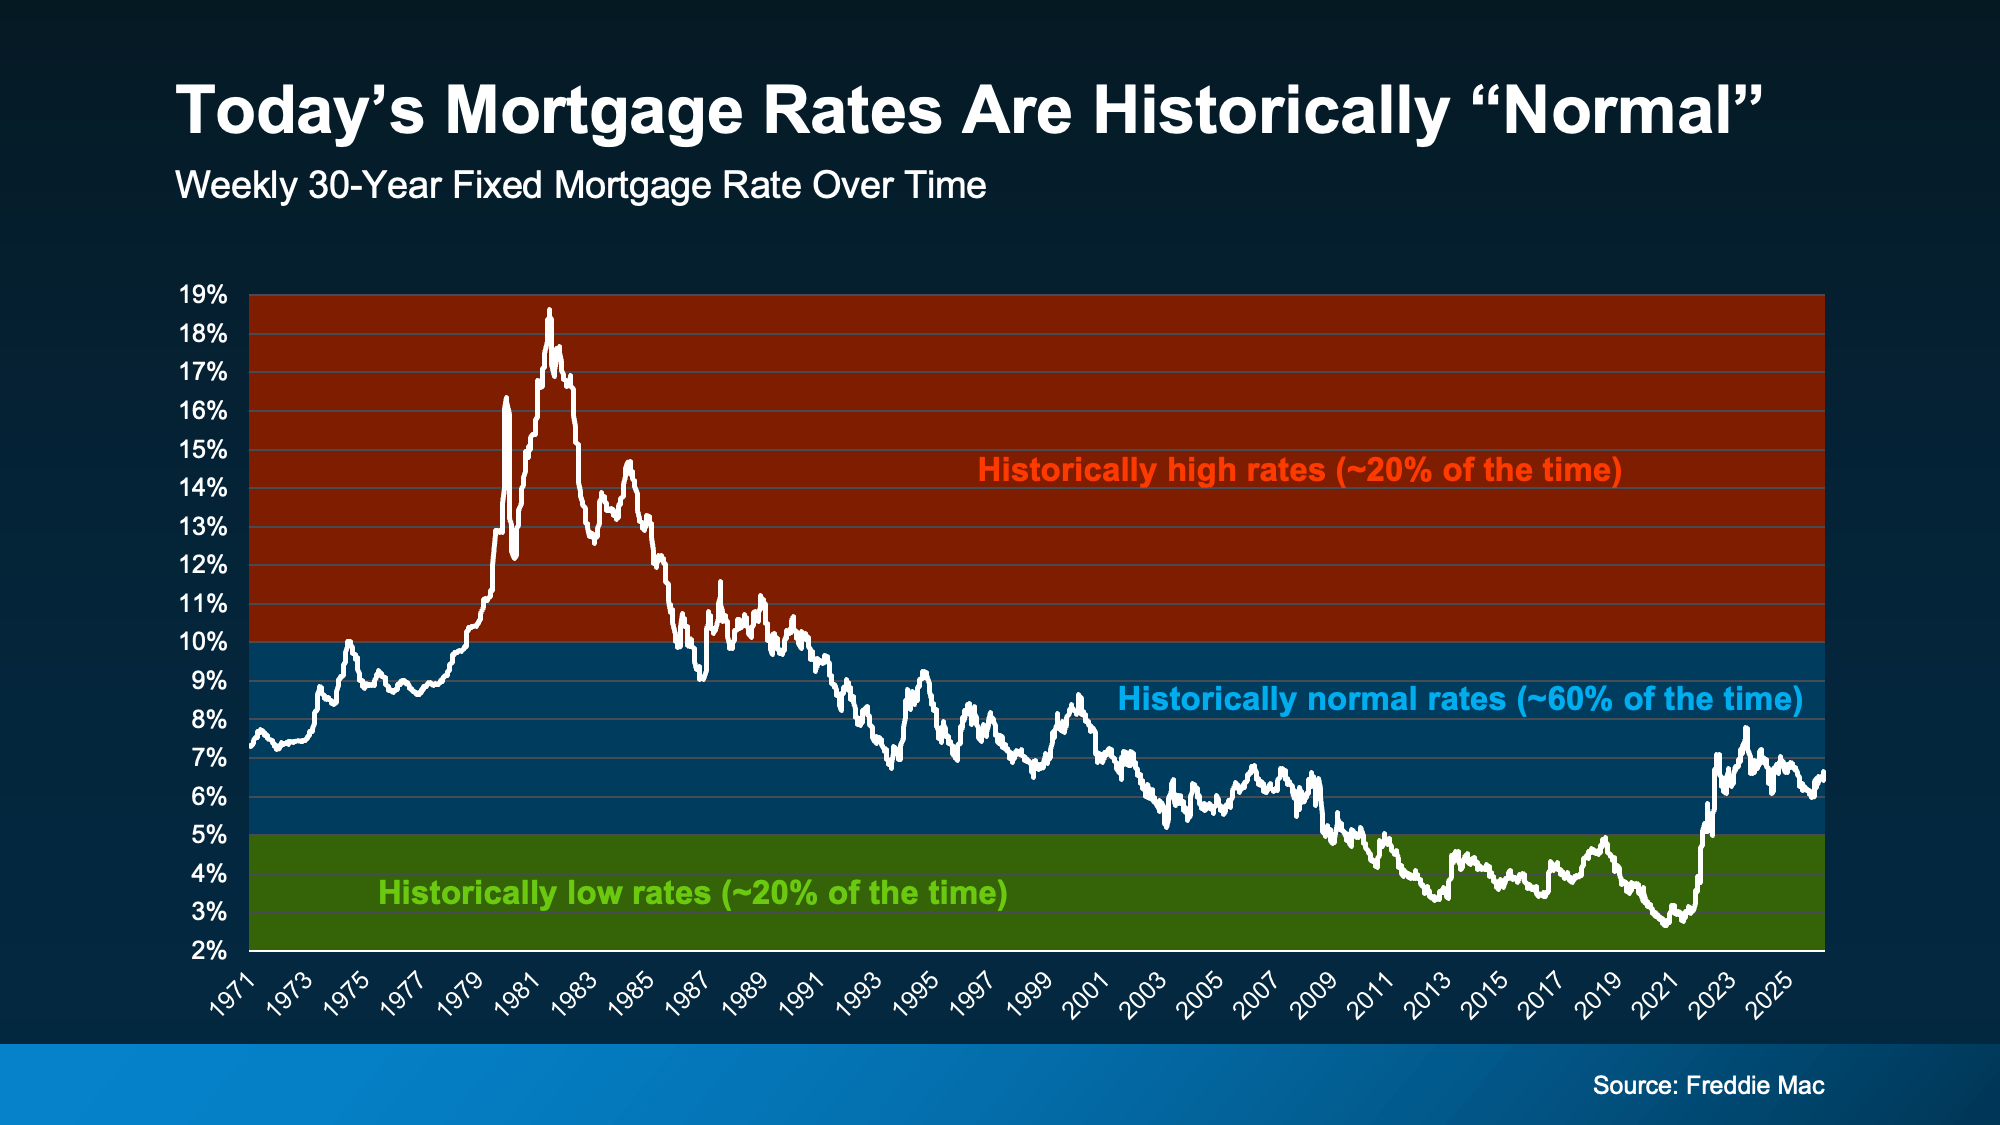
Now, this doesn't suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.
So... What Should You Do Instead?
None of this is meant to convince you that you have to buy today. You don't. But if you need to because something in your life's changed, there are still ways to find better affordability without waiting for mortgage rates to fall.
- Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.
- Ask about an adjustable-rate mortgage (ARM). If you don't plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It's not the right choice for everyone, but it's worth asking a lender if it fits your plans.
- Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get a lower monthly payment without waiting for rates to fall.
- Find out about assumable mortgages. An assumable mortgage allows you to take over the seller's existing loan, including its lower mortgage rate.
The important thing is you shouldn't assume waiting is your only option.
Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.
Watch · Two minutes on timing the market
Bottom Line
Waiting on rates is a strategy. It's just not the only one, and based on today's forecasts, it may not be a fast one either.
Builder incentives, buydowns, and assumable loans all exist in the South Sound right now. Text DiNero your situation and he'll walk you through which of these could actually work for you.
Text DiNero or call (253) 861-2782