Thinking About an Adjustable-Rate Mortgage? Here’s What You Need To Know.
If you’ve been looking for a home lately, you’ve probably felt how tough affordability still is. And that's exactly why more buyers are opting for adjustable-rate mortgages, or ARMs.
Here's what you need to understand about how they work, and whether they make sense for you.
What Is an Adjustable-Rate Mortgage?
Since a lot of people aren’t familiar with this type of loan, let’s start with a definition. This is how Business Insider explains the main difference between a fixed-rate mortgage and an adjustable-rate mortgage:
Basically, one doesn’t change much over the life of your loan.
And one could change... either by a little, or a lot.
Of course, things like taxes or homeowner’s insurance can still have an impact on a fixed-rate loan, but the baseline of your mortgage payment is fairly steady. But the big difference is that with an ARM, your monthly payment could change over time.
Why Adjustable-Rate Mortgages Are Getting More Attention
So, why do some buyers choose this option? It's simple. It’s because of the upfront savings. Business Insider explains it like this:
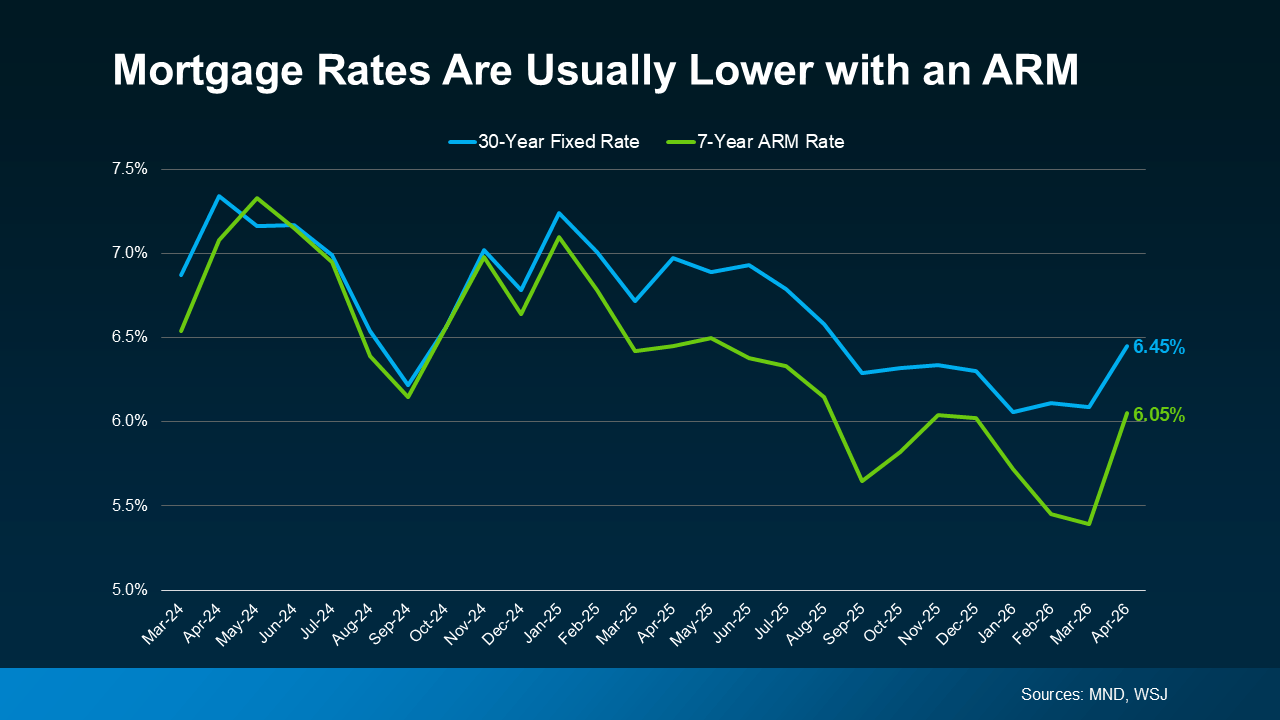
And right now, according to Mortgage News Daily and the Wall Street Journal, the upfront rate on an ARM is lower than a 30-year fixed mortgage (see graph below):
If you’re wondering how that shakes out in real dollars and cents, here’s what Redfin says. According to their research, the typical buyer could save about $150 per month by taking out an ARM instead of a 30-year fixed mortgage.
For some people, that’s enough to make a difference.
More Buyers Are Choosing Adjustable-Rate Mortgages Today
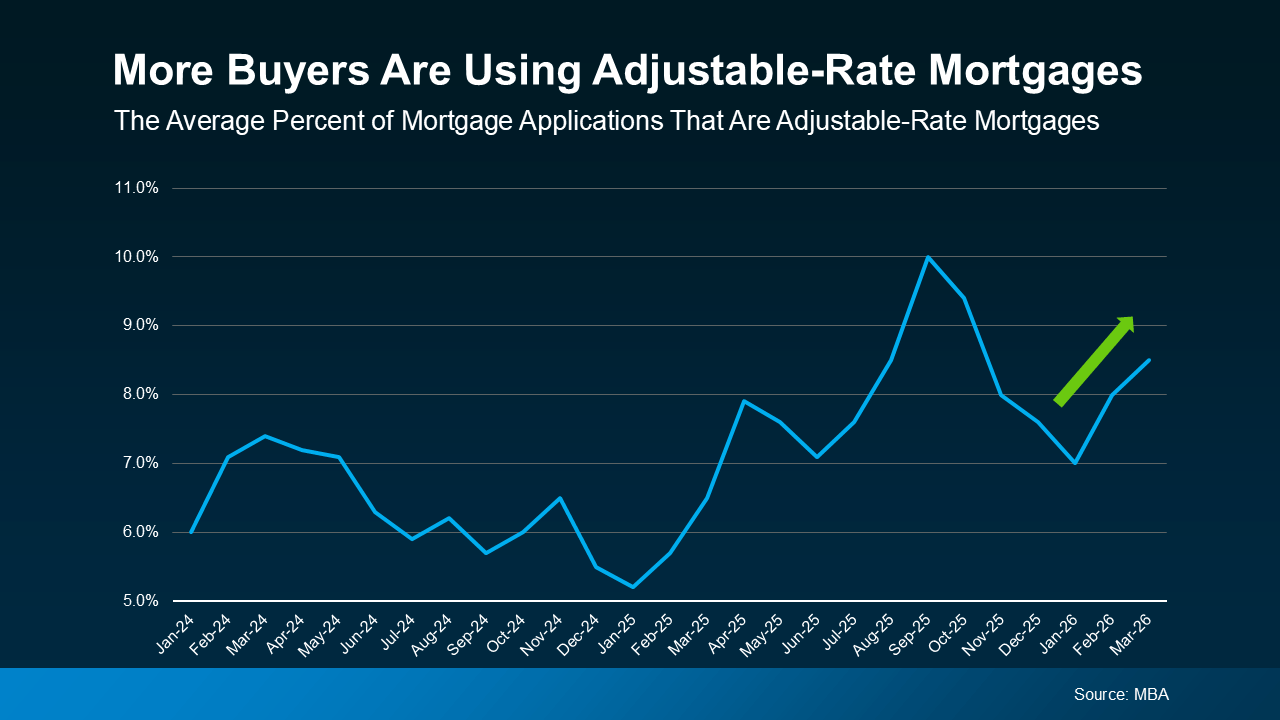
A growing number of buyers are willing to trade the uncertainty later for a lower payment now. Data from the Mortgage Bankers Association (MBA) shows the share of buyers choosing ARMs has increased, especially over the last few years (see graph below).
This doesn’t mean ARMs are becoming the go-to option for everyone. It only means some buyers are opting for this type of mortgage, so they can still buy today.
And if you remember the housing crash, seeing ARMs gain popularity again may raise concerns. But rest easy. Today’s ARMs aren’t the same.
Back then, some buyers were given loans they couldn’t afford once rates adjusted.
Today, lending standards are stricter, and lenders evaluate whether borrowers could still handle the payment if rates rise. So, the return of ARMs doesn’t signal another widespread crash. It just reflects how some buyers are adapting to today’s affordability challenges.
The Trade-Off: What You Need To Consider
If you’re considering an adjustable-rate mortgage yourself, just remember it really all depends on your situation and your risk tolerance.
An ARM may make sense if you plan to move before your rate would adjust or if you expect you’ll make a higher income in the future. But there are trade-offs you need to think through.
For example, once the fixed period ends, your rate can adjust, and your payment could increase, potentially by a meaningful amount depending on where rates are at that time.
And keep in mind, there’s also no guarantee mortgage rates will come down in the future, which means refinancing later isn’t always an option. That’s why it’s important to think through your plan, understand your long-term earning potential, and work closely with a trusted lender before you choose an ARM.
Text DiNero the price range you're considering and he'll show you what today's rates actually look like on South Sound homes.
Text DiNero your range or call (253) 861-2782