Assumable VA loans: how a JBLM buyer can take over a seller's 3 percent rate
Knock Knock Homies!!
I want to talk about the most useful thing in South Sound real estate that almost nobody puts in a listing, and I'm a little annoyed about it. If you are PCSing to JBLM, or you're a veteran anywhere in Pierce County, or you OWN a home with a VA loan you got back in 2020 or 2021, this post is for you. Read the whole thing. Then text me.
Here it is in one sentence: a VA loan can be assumed. That means a buyer can take over the seller's existing mortgage, at the seller's existing interest rate, instead of getting a brand new loan at today's rate. And a big share of the homes around JBLM were bought with VA loans at rates that start with a 2 or a 3.
Let me show you why that matters, how it works, and what it takes to pull it off. And I'm going to be straight with you about the hard parts, because there ARE hard parts.
First, the math, because the math is the whole point
As I'm writing this, Freddie Mac's weekly survey has the average 30-year fixed rate at 6.66 percent (week ending August 27, 2026). Neighbors all over this base locked VA loans in 2020 and 2021 between 2.25 and 3 percent. Same house. Same street. Very different payment.
Say a home in Spanaway is listed at $475,000. The sellers bought it a few years back with a VA loan, and they still owe $380,000 at 2.75 percent with 26 years left on it.
- Assume their loan: $380,000 at 2.75 percent, 26 years left. Principal and interest is about $1,706 a month.
- Get a new loan on that same $380,000 at 6.66 percent over 30 years: about $2,442 a month.
- Difference: about $736 a month. Every month. For years. That's a car payment. That's daycare. That's a lot of trips to the Fair.
Those numbers are principal and interest only, no taxes or insurance, and they're an illustration, not a loan quote. But you see the size of it. This is not a little discount. This is the difference between a house being a stretch and a house being comfortable.
Who can assume a VA loan?
This surprises people: you do NOT have to be a veteran to assume a VA loan. Any buyer who qualifies on credit and income can do it, as long as the loan servicer approves. The VA doesn't require the buyer to be military. It requires that you can pay the loan and that you're going to live in the house. It has to be your primary residence. This is not an investor play.
If you ARE a veteran or active duty, there's an extra wrinkle that matters a lot, and I'll get to it in the seller section, because it affects the person on the other side of the table.
The catch: the equity gap
Here's the part nobody puts in the headline. You're assuming the LOAN, not the price. In our example the house is $475,000 and the loan is $380,000. That $95,000 difference is the seller's equity, and the seller wants it. So you have to bring it: cash, or a second loan, or some combination the servicer will sign off on.
If you're selling a house to buy this one, you might have it. If this is your first home, you probably don't, and that's where gap financing comes in. There are lenders doing second-lien "gap" financing on assumptions in 2026, but it's not a standard product everywhere, the rate on that second loan is higher, and the servicer has to approve it. So when you run the numbers, run them on the BLENDED payment: the assumed loan plus whatever you borrow for the gap. It's usually still a win. It's just not the $736 headline anymore.
Homie tip: the smaller the gap, the better the deal. A seller who bought recently with little down and hasn't seen much appreciation is a GREAT assumption candidate, because the loan balance is close to the price. A seller who bought in 2015 and is sitting on $250,000 of equity is a tough one unless you have real cash.
What it costs and how long it takes
- The VA funding fee on an assumption is 0.5 percent of the loan balance. On our $380,000 loan that's $1,900. Most servicers let you roll it into the loan, and buyers who receive VA disability compensation don't pay it at all.
- The servicer decides, not me and not the listing agent. They underwrite you the same way a new lender would. The VA now requires servicers with automatic authority to make a decision within 45 days of getting your complete package (that's from VA Circular 26-23-27). Some servicers hit that. Some don't. Build in time and stay on them. Your agent should be calling. I will be calling.
- Washington's excise tax still applies to the full sale price. Assuming a loan doesn't change what the state collects on the sale. Sellers, budget for it like any other sale.
Sellers: if you have a VA loan under 4 percent, READ THIS
This is where I get a little fired up. If you bought around JBLM with a VA loan in 2020 or 2021, your mortgage might be the most valuable thing about your house, and most listings don't even mention it.
An assumable 2.75 percent loan is a feature. It's a bigger feature than the new countertops. When we list a home with a low-rate VA loan, that goes front and center in the marketing, because it widens your buyer pool to every family who's been priced out by rates and it can get you a stronger offer.
Now, the wrinkle I promised. Your VA entitlement stays tied to that loan unless the buyer is an eligible veteran who substitutes their own entitlement in your place. If a civilian assumes your loan, you can still get a release of liability so their future default isn't on you, but your entitlement stays parked with that house until the loan is paid off. That can shrink what you're able to borrow with a VA loan on your next house. There is such a thing as second-tier entitlement, and sometimes it's enough, and sometimes it means a down payment. So if you're a seller with orders to your next station and you'll need your VA benefit again, we look hard for a veteran buyer who can do the substitution, or we run the numbers on what's left. Either way, we talk about it BEFORE the sign goes in the yard, not at closing.
Buyers: how to find one
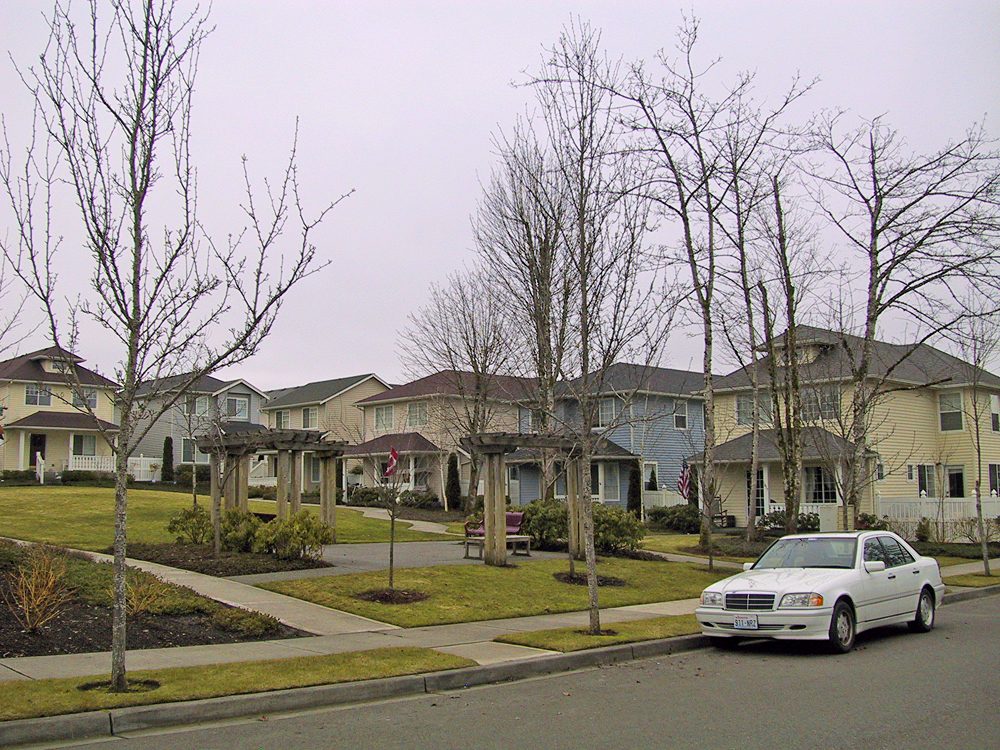
There's no perfect database of assumable homes. Some agents flag it in the listing remarks, a lot don't. Here's how we hunt for them:
- Look at when the seller bought. Purchases from mid-2020 through early 2022 are the sweet spot for low rates.
- Look at where. Spanaway, Parkland, Frederickson, Lakewood, Graham, and the DuPont side of the base have a high share of VA-financed homes. That's just who lives here.
- Ask. Your agent should be calling listing agents and asking, "Is the seller's loan VA, and what's the rate?" I do this. It takes two minutes and it changes the conversation.
- Get your own approval anyway. Assumptions fall through. Servicers say no. Have a regular pre-approval in your back pocket so you're never stuck. Ashley can do that, and so can any lender you trust. You are never required to finance through Ashley to work with us.
Here's where I land, Homies
Rates went up. Good people around this base got priced out of houses they could have afforded three years ago. An assumable VA loan is one of the few honest ways to get some of that back, and it's attached to houses on streets you drive every day.
It takes cash or gap financing, it takes patience with the servicer, and it takes a seller who understands what they're giving up on their entitlement. But when it lines up, it's the best deal in the market. A $736 swing decides whether a family in Spanaway rents another year or buys.
If you're buying, text me and we'll start looking for low-rate loans, not just low-price houses. If you're selling with a VA loan from 2020 or 2021, text me before you list, because we're going to market that rate like it's a second bathroom.
Love where you live. And pay less for it if you can.
DiNero is an Air Force veteran who sells around JBLM every year. Text us whether you're buying or selling and we'll tell you straight whether an assumption makes sense for you.
Text DiNero or call (253) 861-2782